AI Data Centre Spending Is Growing Faster Than the Revenue Meant to Pay for It
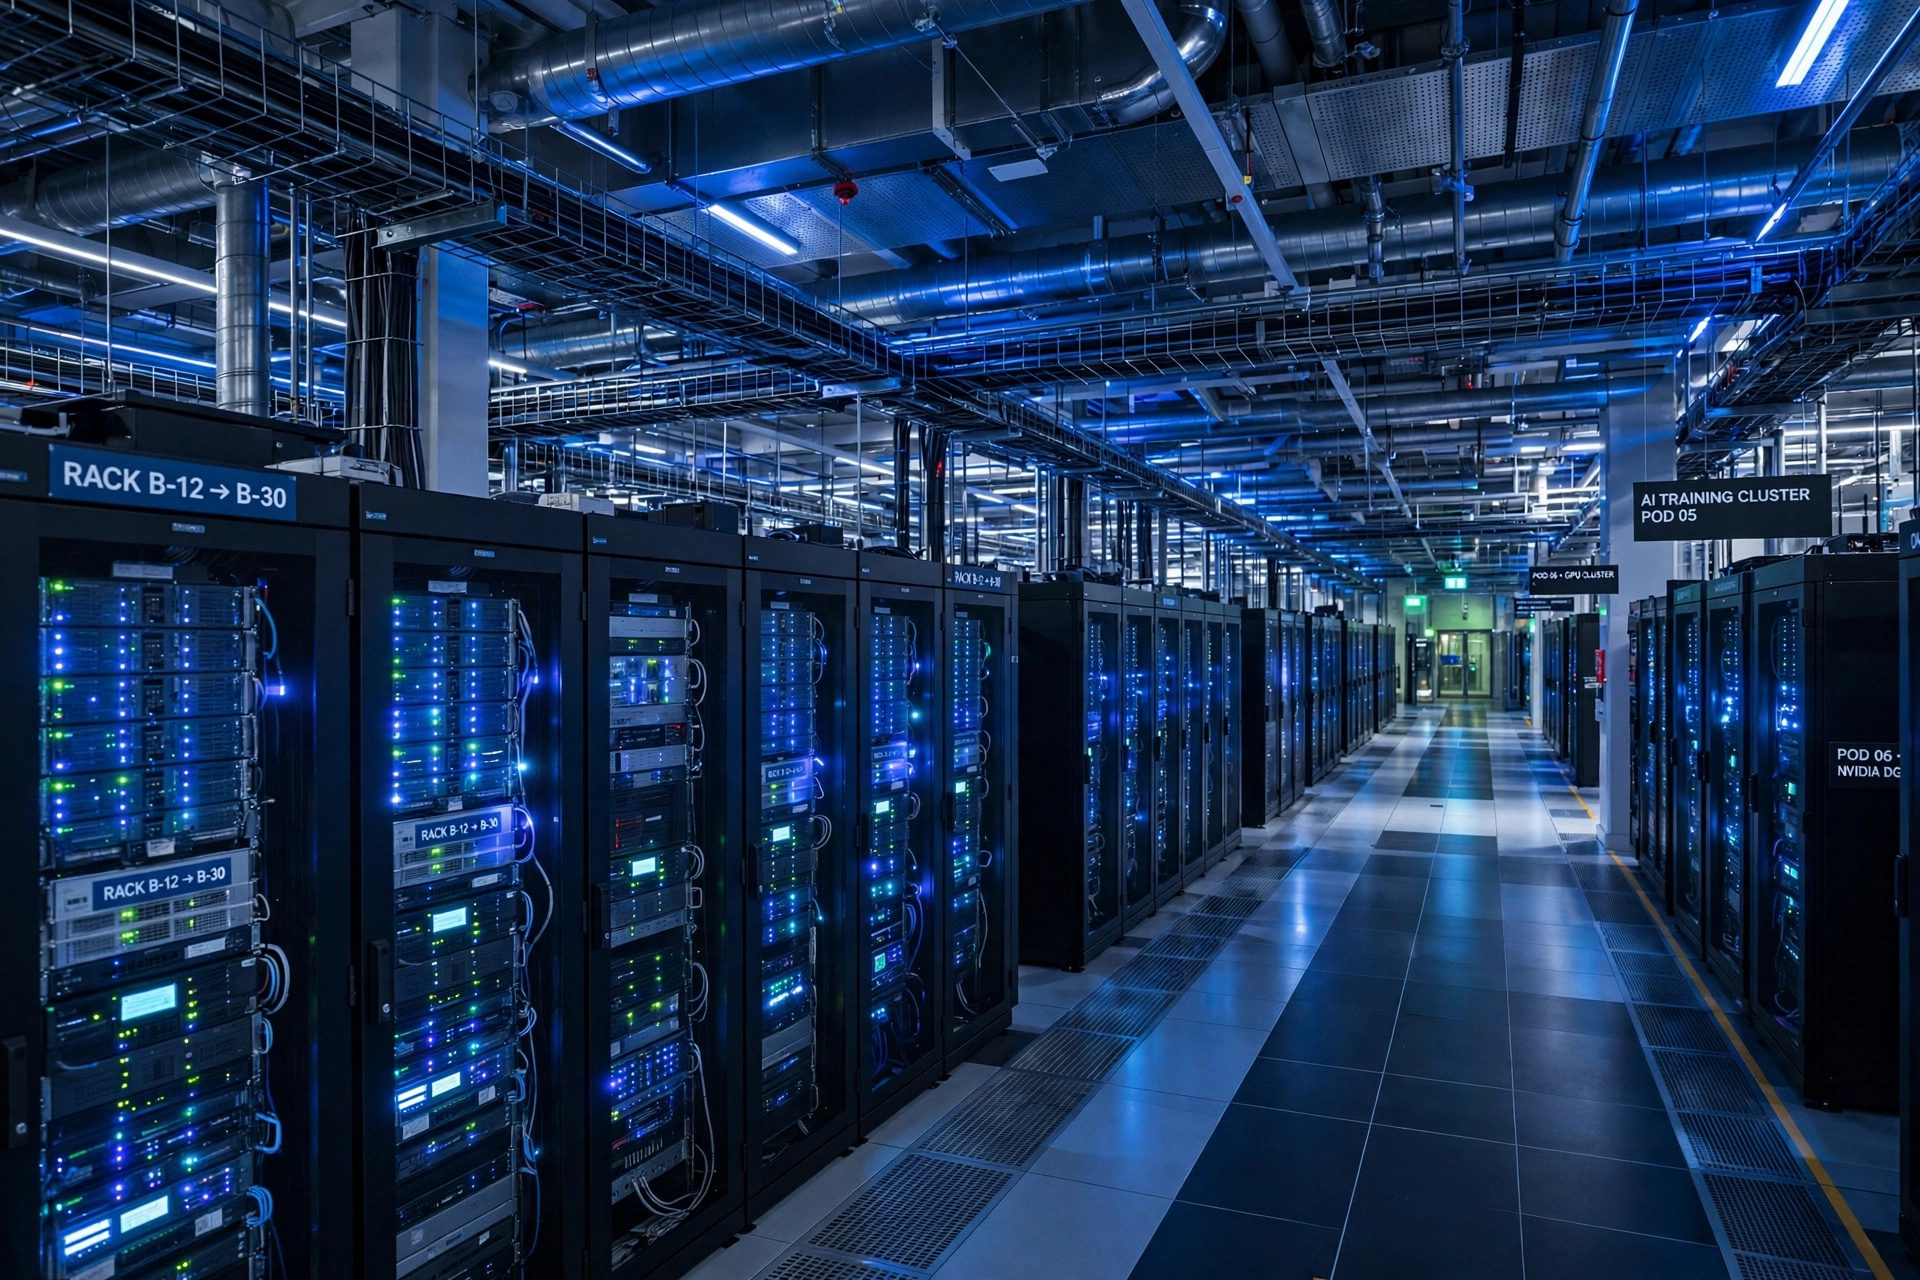
The race to build artificial intelligence infrastructure has become one of the largest spending programmes in technology history. Cloud providers, chip makers and investors are committing enormous sums to data centres, processors, power connections and cooling systems. Yet a growing number of analysts are asking an uncomfortable question: the spending is arriving much faster than the revenue that is supposed to justify it, and the gap between the two is becoming harder to ignore.
The maths behind the warning
Recent industry analysis, reported by The Register, suggests that forecast infrastructure spending on AI is set to outstrip the revenue the technology is expected to generate over the same period. In simple terms, the industry is building the factories before it has proven the size of the market for what those factories produce. Some estimates go further, arguing that paying for the current wave of data centres from AI work alone would require an economy far larger than the one that presently exists.
That does not mean the technology has no value. Businesses are paying for AI assistants, coding tools, customer support automation and data analysis, and usage is growing. The problem is proportion. Enterprise customers tend to adopt new tools gradually, test them against budgets, and cancel what does not save money. Construction, by contrast, is happening at full speed and at full price, with costs for chips, land, energy and skilled labour all rising at the same time.
Why companies keep spending anyway
If the returns are uncertain, why does nobody slow down? Executives give a consistent answer: the risk of being left behind feels larger than the risk of overspending. A cloud provider that under-builds may lose the defining contracts of the next decade, while one that over-builds can hope demand eventually catches up. Investors have so far rewarded that logic, and cheap confidence has kept the cycle turning.
There is also a strategic argument about infrastructure itself. Data centres built for AI can, up to a point, be repurposed for other computing work, and the power connections and buildings retain value even if individual generations of chips age quickly. Supporters say earlier technology waves, from railways to broadband, also looked overbuilt before demand arrived. A separate analysis of what it would take to pay for AI data centres makes a similar point about scale: the sums involved are so large that they reshape labour markets, energy planning and public policy, not just company balance sheets.
Where the pressure will show first
Strain usually appears first at the edges of a boom. Smaller AI companies that rent computing capacity at peak prices may struggle to turn expensive models into profitable products. Regions competing for data centres are being asked for tax breaks, grid upgrades and water for cooling, and local communities are starting to ask what they receive in return. Electricity prices, construction delays and a shortage of specialist engineers can all turn a confident forecast into an expensive problem.
Shareholders are also beginning to ask more precise questions. Instead of celebrating total spending, earnings calls now feature repeated demands to see AI revenue broken out clearly, contract by contract. Companies that can show paying customers renewing and expanding will be treated very differently from those offering only demonstrations and projections. The same scrutiny is visible in consumer technology, where, as our coverage of AI study companions for students shows, users keep the tools that deliver an obvious daily benefit and quietly drop the rest.
A necessary correction, not necessarily a collapse
It is worth separating a correction from a collapse. AI is already embedded in search, software development, design, logistics and education, and those uses will not disappear if spending slows. A more likely outcome is a period of discipline: fewer speculative projects, tougher negotiations over chip and power prices, and a shift of money from raw capacity towards products people demonstrably pay for. Companies with strong cash flow can absorb that adjustment; heavily borrowed newcomers may find it much harder.
For everyone watching from outside the boardrooms, including the businesses now buying AI services, the practical advice is straightforward. Enjoy the falling prices and generous offers that overcapacity produces, but avoid locking essential operations into a single provider whose business model depends on the boom never ending. The build-out is real, and so is the technology. Whether the maths eventually works depends on revenue growing into the enormous foundations now being poured for it, and that answer will be delivered by customers, not by press releases. Readers following how devices carry these services to market can also see our round-up of budget smartphones in India for the consumer end of the same story.


